

19 Years Without Answers: Lawyer Challenges Dangote Over Fate of 2007 IPO Investors, Demands Suspension of 2026 Share.
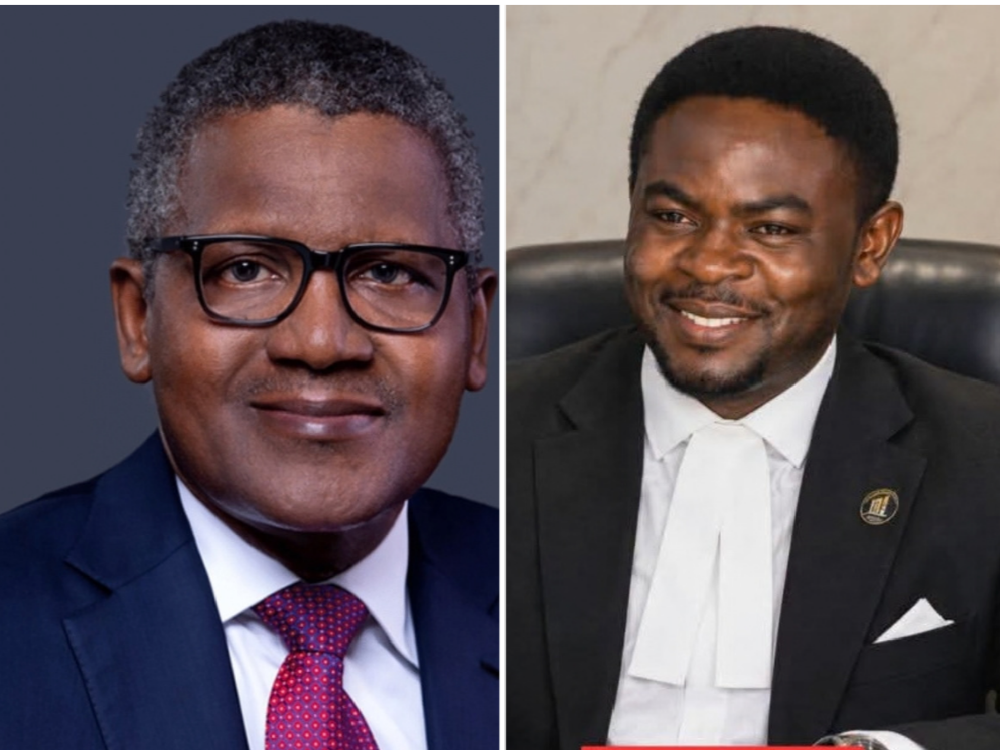
A fresh controversy over investor protection and corporate accountability has emerged following a demand by a Nigerian lawyer for the Dangote Group to account for Nigerians who invested in Dangote Flour Mills Plc during its 2007 Initial Public Offering (IPO), amid renewed public scrutiny of the group’s 2026 share offer.
In a formal letter addressed to the Group Managing Director of Dangote Industries Limited and the Company Secretary of Dangote Flour Mills Plc/Oceanic Registrars Limited, T.O. Teke, Esq., Principal Partner of T.O. Teke Law Office & Co., called for an immediate explanation of the status of the affected investors’ shares, dividends and other possible entitlements.
The lawyer, who identified his firm as a public-interest litigation and human rights advocacy practice, expressed concern that investors who participated in the September 2007 public offer may still be uncertain about what became of their investments following the company’s delisting and subsequent acquisition in 2019.
The demand raises a significant question for Nigeria’s capital market: How can public confidence in new investment opportunities be sustained when questions remain about the treatment of investors from an earlier public offer?
19 Years Later, Investors Deserve Clear Answers
At the centre of the controversy are Nigerians who reportedly subscribed to the 2007 public offer of Dangote Flour Mills Plc, including Sanni Sakariya Abolaji, whose share certificate number was identified in the lawyer’s letter as ORL/DFM/0014406.
According to Teke, affected investors have allegedly gone years without adequate communication concerning their holdings, including information about dividends, bonus shares and the status of their investments.
The lawyer is demanding a comprehensive account of what happened to the shares following the company’s 2019 delisting and acquisition.
Historical records show that Dangote Flour Mills was officially delisted from the Nigerian Stock Exchange, now the Nigerian Exchange (NGX), effective November 18, 2019, following its acquisition by Crown Flour Mills Limited, a Nigerian subsidiary of Olam International. The acquisition was undertaken through a Scheme of Arrangement approved by shareholders.
However, the delisting itself does not establish that shareholders’ investments were abandoned or that their entitlements remain unpaid. The key issue is whether the terms of the acquisition and scheme were properly implemented for every affected shareholder, and whether outstanding claims remain unresolved.
For investors who cannot establish the present status of their holdings, the demand for accessible records and a transparent verification process is central to resolving the matter.
Lawyer Demands Suspension of 2026 Share Offer
Teke’s intervention comes amid heightened public attention surrounding the Dangote Group’s 2026 share offering, which has attracted scrutiny from social commentator Martins Vincent Otse, popularly known as VeryDarkMan.
VeryDarkMan has publicly criticised the Dangote Refinery IPO, questioning aspects of the investment campaign and reportedly describing it as resembling a Ponzi scheme. His criticism has added to the wider public debate over transparency, investor confidence and the treatment of Nigerians participating in major investment opportunities.
However, the 2026 Dangote Refinery offering must be distinguished from the 2007 Dangote Flour Mills IPO. They concern different corporate entities and investments.
The Securities and Exchange Commission (SEC) announced on September 14, 2026, that the Initial Public Offering of Dangote Petroleum Refinery and Petrochemicals FZE had received regulatory approval to open. The Commission also cautioned investors to use officially approved subscription channels and verify investment information before making payments.
Against this background, Teke is calling for the suspension of the new offer until the concerns surrounding the 2007 Flour Mills investors are addressed.
In his letter, the lawyer stated:
“You cannot seek new investors when you have abandoned the old ones and their money is generating billions of Naira to your company.”
The statement reflects the lawyer’s position that unresolved concerns involving previous investors should be addressed before the company seeks fresh public investment. His allegation that existing investors have been abandoned, however, requires a response from the companies concerned and verification against the terms of the 2019 acquisition.
Four Demands Put Before Dangote Group
In his letter, Teke outlined four major demands, giving the companies 14 days to publish a comprehensive statement on the status of the 2007 IPO investors.
1. Full disclosure of shareholders’ status . The lawyer wants Dangote Industries Limited and the relevant corporate entities to explain what happened to the holdings of investors who participated in the 2007 public offer, including how their shares were treated following the 2019 transaction.
2. Public accounting of dividends and entitlements. He is demanding a transparent account of any unclaimed dividends, bonus shares and other benefits that may be due to the affected investors.
3. Suspension of the 2026 share offer. Teke wants the new share offer suspended until the outstanding concerns involving the 2007 investors have been resolved and any established entitlements paid.
4. Creation of a dedicated claims platform. The lawyer is also demanding a transparent portal and help desk through which affected investors can verify their identities, confirm their holdings and pursue outstanding claims within 30 days.
The letter was copied to the Director-General of the Securities and Exchange Commission, the Managing Director of the Central Securities Clearing System (CSCS) Plc, the Executive Vice Chairman of the Federal Competition and Consumer Protection Commission (FCCPC), and the Director-General of the Nigerian Exchange Group.
The National Question: Who Protects the Ordinary Investor?
Beyond the dispute involving Dangote Flour Mills, the controversy raises broader questions about investor protection and public confidence in Nigeria’s capital market.
For many ordinary Nigerians, investing in a public offer represents an opportunity to participate in the growth of major companies. Such participation, however, depends on access to reliable information, transparent corporate processes and effective channels for resolving disputes.
Where investors are unable to establish the status of their holdings, the resulting uncertainty can undermine confidence not only in the company involved, but also in the institutions responsible for protecting investors.
The central issue is therefore not simply whether a new share offer should proceed. It is whether investors from previous offerings have received the treatment and information to which they are entitled under the applicable terms and laws. The SEC’s recent guidance on the Dangote Refinery IPO reinforces the importance of verified information, approved subscription channels and investor awareness.
Nevertheless, determining whether the 2007 investors are owed outstanding benefits requires examination of the original offer documents, the 2019 Scheme of Arrangement, shareholder records and any payments or settlements made under that transaction.
What Dangote Group and Regulators Need to Clarify
To address the concerns raised, the relevant companies would need to explain:
What consideration or other entitlements were provided to shareholders under the 2019 Scheme of Arrangement.
Whether any dividends or other benefits remain unclaimed or unpaid.
What procedures are available to investors who have lost contact with the registrars or cannot verify their shareholdings.
Whether complaints have been received from affected shareholders and how they have been handled.
The companies’ response would help establish whether the matter involves unpaid entitlements, difficulties with shareholder verification, inadequate communication or other issues arising from the acquisition.
As of the information available for this report, the lawyer’s letter sets out demands and allegations; it does not, by itself, establish that all 2007 investors were deprived of their investments or that the 2026 offer is unlawful.
Conclusion: Transparency Must Come Before Public Trust
The demand by T.O. Teke places a matter of public interest before Dangote Industries Limited, the relevant registrars and Nigeria’s capital-market regulators.
The affected investors deserve clear information about the fate of their holdings, while the companies concerned deserve an opportunity to explain how the 2019 transaction was implemented.
If outstanding entitlements are established, they should be addressed through the appropriate procedures. If the investors’ interests were settled under the acquisition, the relevant records should make that clear.
For a country seeking to expand public participation in its capital market, confidence cannot rest on new investment campaigns alone. It also depends on transparent records, accessible remedies and demonstrable accountability to existing shareholders.
The pressing question remains: Will Dangote Group publicly clarify the position of the 2007 Flour Mills investors and address any outstanding claims as calls for accountability intensify?